IPO

Saturday, November 26, 2022

ITMAX SYSTEM BERHAD

Copyright@http://lchipo.blogspot.com/
Follow us on facebook: https://www.facebook.com/LCH-Trading-Signal-103388431222067/


***Important***Blogger is not wrote any recommendation & suggestion. All is personal opinion and reader should take their own risk in investment decision.
Open to apply: 25/11/2022
Close to apply: 01/11/2022
Balloting: 05/12/2022
Listing date: 13/12/2022

Share Capital
Market cap: mil (will depend on final IPO price)
Total Shares: 1.028bil shares
 
Industry CARG (2017-2021)
GVA of Digital Economy: 6%
Competitors Netprofit margin%
ITMAX Group: 36.7%
EV-Dynamic S/B: 1.7%
Signify Malaysia S/B: 1.6%
TNB Research S/B: 3.5%
ITRAMAS Corporation S/B: 2.0%
Industronics Bhd: -11.8%
Turbine Technique (M) S/B: 9.9%
Norangkasa Enterprise S/B: 1.0%
VADS Lyfe S/B: 40.4%

Business (FYE 2022)
Supply and installation and provision of public space networked systems. 
(Networked lighting systems, networked traffic management system, Networked video survelliance facilities, & other for local gov & ministry, telecommuications services providers.)
Revenue by Geo
Msia: 100% (Selangor, KL, Sabah)

Fundamental
1.Market: Main Market
2.Price: RM1.07
3.P/E: 37.7 @ RM0.0284 (PE will difference if final IPO price is not RM1.07)
4.ROE(Pro Forma III): 12.03%
5.ROE: 54.22%(FYE2021), 41.28%(FYE2020), 8.83%(FYE2019)
6.NA after IPO: RM0.25
7.Total debt to current asset after IPO: 0.456 (Debt: 115.185mil, Non-Current Asset: 119.718mil, 
Current asset: 252.331mil)
8.Dividend policy: target 20% PAT dividend policy. 
9. Shariah starus: Yes

Past Financial Performance (Revenue, Earning Per shares, PAT%)
2022 (FYE 30Jun, 6mths): RM40.740 mil (Eps: 0.01503),PAT: 37.9%
2021 (FYE 31Dec): RM79.759 mil (Eps: 0.02844),PAT: 36.7%
2020 (FYE 31Dec): RM47.538 mil (Eps: 0.01232),PAT: 26.7%
2019 (FYE 31Dec): RM37.212 mil (Eps: 0.00153),PAT: 4.2%

Major customer (2022)
1. DBKL: 94.5%
2. Norangkasa Enterprise Sdn Bhd: 2.0%
3. Bank Rakyat: 0.9%
4. Wbe Digital Sdn Bhd: 0.6%
5. Ahmad Zaki Sdn Bhd: 0.5%
***total 98.5%
***DBKL Remaining order book: 438mil (until 2029), 10.757mil(until 2023), 60.740mil(until2023)

Major Sharesholders
Tan Sri Dato’ (Dr.) Tan Boon Hock: 51.3% (indirect)
Datin Afinaliza: 17.6% (indirect)
Tan Wei Lun: 51.3% (indirect)
Directors & Key Management Remuneration for FYE2023 (from Revenue & other income 2022)
Total director remuneration: RM1.443mil
key management remuneration: RM0.80mil - RM0.95mil
total (max): RM2.393 mil or 4.48% 

Use of funds
1. Smart city application expansion to other local governments, federal ministries, and existing customers: 41.7%
2. Expansion of R&D capabilities: 6.1%
3. Expansion into enterprise market: 9.8%
4. Network and telecommunication infrastructure expansion: 19.4%
5. Working capital: 14.3%
6. Repayment of borrowings: 3.9%
7. Listing Expenses: 4.8%
Conclusions (Blogger is not wrote any recommendation & suggestion. All is personal opinion and reader should take their own risk in investment decision)
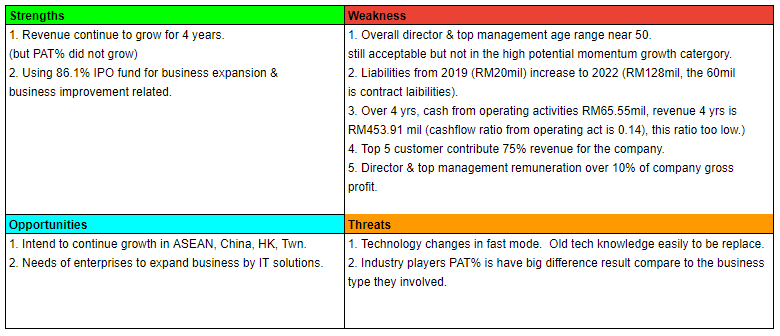
Overall is a non-discount IPO. The company have opportunities to grow but investor also must aware on the issue of over depend into single customer DBKL. (please refer to the above SWOT analysis table). 

*Valuation is only personal opinion & view. Perception & forecast will change if any new quarter result release. Reader take their own risk & should do own homework to follow up every quarter result to adjust forecast of fundamental value of the company.

Saturday, November 5, 2022

ECA INTEGRATED SOLUTION BERHAD

Copyright@http://lchipo.blogspot.com/
Follow us on facebook: https://www.facebook.com/LCH-Trading-Signal-103388431222067/

***Important***Blogger is not wrote any recommendation & suggestion. All is personal opinion and reader should take their own risk in investment decision.
Open to apply: 04/11/2022
Close to apply: 11/11/2022
Balloting: 16/11/2022
Listing date: 23/11/2022

Share Capital
Market cap: RM98.175mil
Total Shares: 577.5mil shares
 
Industry CARG (2015-2021)
Global automated manufacturing solutions industry: 7.9%
Automated manufacturing solutions industry in Malaysia: 17.5%
Competitors PAT%
ECA Integrated Group: 39.9%
Aimflex Berhad:6.2% PE18
BBS Automation Penang Sdn Bhd:78.8%
DNC Automation (M) Sdn Bhd:1.0% 
Genetec Technology Berhad:26.0% PE21
Greatech:35.2%, PE38
Pentamaster:17.1%, PE33
Vitrox: PE33

Business (FYE 2022)
Automated manufacturing solution provider.
1.Integrated production systems: 84.6%
2.Standalone automated equipment: 9.9%
3.After sales service to our customers for the provision of technical support services and spare parts: 5.5%
Revenue by Geo
1. Msia: 34.2%
2. Europe: 16.1%
3. Asia: 7.0%
4. North America: 42.7%

Fundamental
1.Market: Ace Market
2.Price: RM0.17
3.P/E: 11.97 @ RM0.0142
4.ROE(Pro Forma III): 15.4%
5.ROE: 48%(FYE2022), %(FYE2021), 62.8%(FYE2020), 47.3%(FYE2019)
6.NA after IPO: RM0.08
7.Total debt to current asset after IPO: 0.21 (Debt: 10.706mil, Non-Current Asset: 5.950mil, Current asset: 49.075mil)
8.Dividend policy: target 20% PAT dividend policy. 
9. Shariah starus: -

Past Financial Performance (Revenue, Earning Per shares, PAT%)
2022 (FYE 30Jun, 8mths): RM17.816 mil (Eps: 0.0079),PAT: 25.7%
2021 (FYE 31Oct): RM20.511 mil (Eps: 0.0142),PAT: 39.9%
2020 (FYE 31Oct): RM15.367 mil (Eps: 0.0096),PAT: 36.2%
2019 (FYE 31Oct): RM7.671 mil (Eps: 0.0024),PAT: 17.8%

Major customer (2022)
1. Customer B5: 42.4%
2. Customer H: 18.7%
3. Customer C: 10.8%
4. Customer B2: 10.0%
5. Customer A2: 7.1%
***total 89.0%

Major Sharesholders
Mr.Ooi: 24.3%
Mr.Chua: 27.8%
Mr.Kang: 13.6%

Directors & Key Management Remuneration for FYE2023 (from Revenue & other income 2022)
Total director remuneration: RM1.335mil
key management remuneration: RM0.70mil - RM0.850mil
total (max): RM2.185 mil or 19% 

Use of funds
1. Acquisition of machineries: 30.2%
2. Repayment of bank borrowings: 3.9%
3. Working capital: 54.9%
5. Listing Expenses: 11%%
Conclusions (Blogger is not wrote any recommendation & suggestion. All is personal opinion and reader should take their own risk in investment decision)
Overall is a slightly above normal IPO. Investor need to take note on the cash operating cashflow is not strong, & need to be monitor for every QR result. 

*Valuation is only personal opinion & view. Perception & forecast will change if any new quarter result release. Reader take their own risk & should do own homework to follow up every quarter result to adjust forecast of fundamental value of the company.

Tuesday, November 1, 2022

INFOMINA BERHAD

Copyright@http://lchipo.blogspot.com/
Follow us on facebook: https://www.facebook.com/LCH-Trading-Signal-103388431222067/


***Important***Blogger is not wrote any recommendation & suggestion. All is personal opinion and reader should take their own risk in investment decision.
Open to apply: 01/11/2022
Close to apply: 11/11/2022
Balloting: 16/11/2022
Listing date: 25/11/2022

Share Capital
Market cap: RM240.5 mil
Total Shares: 601.250mil shares
 
Industry CARG
Enterprise IT services industry in Malaysia: 2%
Competitors PAT%
Censof: 18.1%
Dagang Net Technologies Sdn Bhd: -38.3%
Dataprp: -30.6%
Dsonic: 7.5%
Excel Force: 32.6%
HTPadu: -6.1%
Iris: 1.6%
Msniaga: 2.3%
Myeg: 43.9%
N2N: 17.6%
Omesti: -2.9%
Scicom: 11.9%
 
Business (FYE 2022)
Design and implementation of technology application and infrastructure solutions that support the fundamental business operations.
Design and delivery of technology infrastructure solutions: 50.3%
Technology infrastructure operations, maintenance and support services: 49.7%
Revenue by Geo
Msia: 57.4%
Thailand: 16.2%
Philippines: 21.1%
Others: 5.3%

Fundamental
1.Market: Ace Market
2.Price: RM0.40
3.P/E: 14.08 @ RM0.0284 (using difference EPS, pls refer reason on financial performance part)
4.ROE(Pro Forma III): 24.13%
5.ROE: 57.60%(FYE2022), 54.69%(FYE2021), 32.27%(FYE2020), 60.62%(FYE2019)
6.NA after IPO: RM0.12
7.Total debt to current asset after IPO: 0.68 (Debt: 128.173mil, Non-Current Asset: 11.502mil, Current asset: 187.457mil)
8.Dividend policy: no formal dividend policy. 
9. Shariah starus: yes

Past Financial Performance (Revenue, Earning Per shares, PAT%)
2022 (FYE 31May): RM201.063 mil (Eps: 0.0284),PAT: 8.5%
2021 (FYE 31May): RM105.224 mil (Eps: 0.0137),PAT: 7.8%
2020 (FYE 31May): RM81.616 mil (Eps: 0.0056),PAT: 4.1%
2019 (FYE 31May): RM66.006 mil (Eps: 0.0114),PAT: 10.5%
*EPS in prospecture book pg206 not use enlarged 601.250mil shares, EPS above using manual count on enlarged 601.250mil shares after IPO. 

Order Book
2023: RM160.3
2024: RM72.1
2025: RM58.2
2026: RM42.2
2027: RM13.4

Major customer (2022)

1. Customer K: 24.5%
2. Customer J: 23.3%
3. The Siam Commercial Bank: 10%
4. Customer P: 9.7%
5. Customer H: 7.5%
***total 75%

Major Sharesholders
Infomina Holdings: 55.4% (Direct)
Yee Chee Meng: 6.3% (Direct)
Lim Leong Ping @ Raymond Lim: 5.9% (Direct)
Nasimah Binti Mohd Zain: 55.4% (Indirect)
Mohd Hoshairy Bin Alias: 55.4% (Indirect)
Tan Siang Pin: 5.2%

Directors & Key Management Remuneration for FYE2023 (from Revenue & other income 2022)
Total director remuneration: RM3.434mil
key management remuneration: RM3.35 mil - RM3.55mil
total (max): RM6.984 mil or 16.67% 

Use of funds
1. R&D: 23.4%
2. Regional expansion: 17%
3. Branding, marketing & promotional activities: 2.7%
4. Working capital: 43%
5. Listing Expenses: 13.9%

Conclusions (Blogger is not wrote any recommendation & suggestion. All is personal opinion and reader should take their own risk in investment decision)
Overall is a high grow company but also come with high risk on their over top 5 customer focus & also their financial statement healthy performance. Investor invest in this stock need to always monitor their company QR & more monitor the risk involved.  

*Valuation is only personal opinion & view. Perception & forecast will change if any new quarter result release. Reader take their own risk & should do own homework to follow up every quarter result to adjust forecast of fundamental value of the company.
Friday, October 28, 2022

LEFORM BERHAD

Copyright@http://lchipo.blogspot.com/
Follow us on facebook: https://www.facebook.com/LCH-Trading-Signal-103388431222067/

***Important***Blogger is not wrote any recommendation & suggestion. All is personal opinion and reader should take their own risk in investment decision.
Open to apply: 26/10/2022
Close to apply: 11/11/2022
Balloting: 15/11/2022
Listing date: 22/11/2022

Share Capital
Market cap: RM340 mil
Total Shares: 1.481bil shares
 
Industry CARG
Malaysia steel manufacturing sales value (2018-2021): CAGR5.4%
Competitors historical PAT% range & current PE.
ChooBee: -0.3% to 20.3%, PE2.27
Astino: 4.1% to 11%, PE4.58
ATTA: -0.27% to 17.7%, PE84.38
Engtex: -0.1% to 6.5%, PE9.27
LSteel: -5.5% to 11.4%, PE3.95
LeonFB: 0.9% to 15.3% ,PE1.56
Melewar: -10.2% to 4.7% ,PE2.25
Prestar: 1.2% to 17.7%,PE1.82
Tashin: 0.2% to 16.1%  ,PE2.44

Business (FYE 2022)
Manufacturing of and trading in steel products. 
Revenue by Geo:
M'sia: 98.4%
Others: 1.6%

Fundamental
1.Market: Ace Market
2.Price: RM0.23
3.P/E: 14.4 @ RM0.016
4.ROE(Pro Forma III): 9.73%
5.ROE: 26.74%(FYE2021), 5.68%(FYE2020), -%(FYE2019)
6.NA after IPO: RM0.17
7.Total debt to current asset after IPO: 0.696 (Debt:261.109mil, Non-Current Asset: 136.017mil, Current asset: 374.917mil)
8.Dividend policy: no formal dividend policy. 
9. Shariah status: yes

Past Financial Performance (Revenue, Earning Per shares, PAT%)
2022 (FYE 30Jun): RM213,671 mil (Eps: 0.008),PAT: 5.7%
2021 (FYE 31Dec): RM373,974 mil (Eps: 0.030),PAT: 12.1%
2020 (FYE 31Dec): RM354,714 mil (Eps: 0.004),PAT: 2.0%
2019 (FYE 31Dec): RM344,581 mil (Eps: -0.001),PAT: -0.5%
 
Major customer (2022)
1. Noblelift Malaysia Sdn Bhd: 13.3%
2. Pipeworks Sdn Bhd: 7.6%
3. Tai Hoe Hardware Sdn Bhd: 4.3%
4. Metro Supplies Marketing S/B: 3.0%
5. Machmar Industries S/B: 2.8%
***total 29.00%

Major Sharesholders
1. Law Kok Thye: 51% (indirect)
2. Tianwen Holdings: 51% (Direct)

Directors & Key Management Remuneration for FYE2022 (from Revenue & other income 2022)
Total director remuneration: RM3.215mil
key management remuneration: RM0.7 mil - 0.9mil
total (max): RM4.115 mil or 8.11% 

Use of funds
1. Construction of new headquarters, warehouse storage facility and workers’ accommodation: 42%
2. Repayment of bank borrowings: 20.1%
3. Working capital: 30.6% 
5. Listing Expenses: 7.3%
Conclusions (Blogger is not wrote any recommendation & suggestion. All is personal opinion and reader should take their own risk in investment decision)
Overall this IPO is not suitable to low risk investor, as the commodities fluctuation will cause big effect to the company net profit in future. 

*Valuation is only personal opinion & view. Perception & forecast will change if any new quarter result release. Reader take their own risk & should do own homework to follow up every quarter result to adjust forecast of fundamental value of the company.

Thursday, September 29, 2022

BETAMEK BERHAD

Copyright@http://lchipo.blogspot.com/
Follow us on facebook: https://www.facebook.com/LCH-Trading-Signal-103388431222067/

***Important***Blogger is not wrote any recommendation & suggestion. All is personal opinion and reader should take their own risk in investment decision.
Open to apply: 28/09/2022
Close to apply: 07/10/2022
Balloting: 12/10/2022
Listing date: 26/10/2022

Share Capital
Market cap: RM225mil
Total Shares: 450mil shares
 
Industry CARG
2019-2021 industry CAGR: 3.8%
Competitors PAT%
Ataims: -0.5%
VS industry Berhad: 6%
EG Industries Berhad: 1.3%
Delloyd Electronics (M) Sdn Bhd: 10.7%
Others: loss to 9.6%

Business (FYE 2022)
Automotive electronics manufacturing services. 
Revenue: 95% (Perodua - main customer)

Fundamental
1.Market: Ace Market
2.Price: RM0.50
3.P/E: 16.7 @ RM0.03
4.ROE(Pro Forma III): 10.88%
5.ROE: 14.41%(FYE2022), 14.03%(FYE2021), 13.46%(FYE2020), 29.85%(FYE2019)
6.NA after IPO: RM0.28
7.Total debt to current asset after IPO: 0.37 (Debt:37.779mil, Non-Current Asset: 60.555mil, Current asset: 101.007mil)
8.Dividend policy: no formal dividend policy. 
9. Shariah starus: Shariah compliant.

Past Financial Performance (Revenue, Earning Per shares, PAT%)
2022 (FYE 31Mar): RM133.051 mil (Eps: 0.030),PAT: 10.1%
2021 (FYE 31Mar): RM129.869 mil (Eps: 0.027),PAT: 9.4%
2020 (FYE 31Mar): RM130.732 mil (Eps: 0.024),PAT: 8.3%
2019 (FYE 31Mar): RM126.542 mil (Eps: 0.051),PAT: 18.1%
 
Major customer (2022)
1. Perodua manufacturing: 51.4%
2. Perodua Global Manufacturing: 37.6%
3. Perodua Sales: 6%
4. HIL Industries: 1.9%
5. Sipro Plastic: 1.6%
***total 98.5%

Major Sharesholders
Iskandar Holdings: 72% (Direct)
Mirzan Bin Mahathir: 72% (Indirect)

Directors & Key Management Remuneration for FYE2023 (from Revenue & other income 2022)
Total director remuneration: RM0.962mil
key management remuneration: RM1.156 mil - 1.450mil
total (max): RM2.412 mil or 9.83% 

Use of funds
1. R&D - new product development: 20.7%
2. To expand R&D office space, raw material storage and ancillary facilities: 19.3%
3. Purchase of new process equipment: 8.9%
4. Working capital requirement: 11.4%
5. Repayment bank borrowing: 29.6%
6. Listing Expenses: 10.1%
Conclusions (Blogger is not wrote any recommendation & suggestion. All is personal opinion and reader should take their own risk in investment decision)
Refer to above SWOT analysis. Overall is a high risky business model as over focus on single customer (Perodua, 95% of company revenue). Sumore their industry itself is very competitive industry. 

*Valuation is only personal opinion & view. Perception & forecast will change if any new quarter result release. Reader take their own risk & should do own homework to follow up every quarter result to adjust forecast of fundamental value of the company.

Monday, September 26, 2022

SUNVIEW GROUP BERHAD

Copyright@http://lchipo.blogspot.com/
Follow us on facebook: https://www.facebook.com/LCH-Trading-Signal-103388431222067/

***Important***Blogger is not wrote any recommendation & suggestion. All is personal opinion and reader should take their own risk in investment decision.
Open to apply: 23/09/2022
Close to apply: 30/09/2022
Balloting: 04/10/2022
Listing date: 17/10/2022

Share Capital
Market cap: RM135.720 mil
Total Shares: 468mil shares
 
Industry CARG
Global solar installation CAGR 2017-2021: 21.3%
Msia Solar PV Installed CAGR 2017-2021: 45.9%
Crystalline Silicon Module Price CAGR: RM/W 16.4%
-Msia Gov committed to use renewable resources: 2025 (31%), 2035 (40%).   
-In 2021 Msia renewable energy installed: 23%
Competitors PAT%
Solarvest: 4.2% (PE45.16)
Pekat: 3.9% (PE24.10)
Sunview: 9% (PE15.27)
Samaiden: 11% (PE24.07)
El Power Technologies Sdn Bhd: 3.9%
 
Business (FYE 2022)
EPCC of Solar PV facilities: 75.73%
Construction & Installation Solar PV facilities: 8.85%
Associated services & products: 11.9%
Solar power generation & supply: 3.52%

Fundamental
1.Market: Ace Market
2.Price: RM0.29
3.P/E: 15.27 @ RM0.019
4.ROE(Pro Forma III): 9.88%
5.ROE: 16.24%(FYE2022), 51.76%(FYE2021), 48.14%(FYE2020), -%(FYE2019)
6.NA after IPO: RM0.19
7.Total debt to current asset after IPO: 0.51 (Debt:92.975mil, Non-Current Asset: 56.462mil, Current asset: 182.895mil)
8.Dividend policy: no formal dividend policy. 
9. Shariah starus: - 

Past Financial Performance (Revenue, Earning Per shares, PAT%)
2022 (FYE 31Mar): RM99.263 mil (Eps: 0.0190),PAT: 8.95%
2021 (FYE 31Mar): RM43.330 mil (Eps: 0.0124),PAT: 13.36%
2020 (FYE 31Mar): RM26.375 mil (Eps: 0.0054),PAT: 9.59%
2019 (FYE 31Mar): RM5.651 mil (Eps: -0.0015),PAT: -%
 
Major customer (2022)
Customer A: 14.01%
Adil Bestari Sdn Bhd: 12.97%
GV Bumi Sandakan Sdn Bhd: 10.83%
Sinohydro Corporation Sdn Bhd: 8.6%
Malakoff Radiance Sdn Bhd:5.59%
***total 52.00%

Major Sharesholders
NEC: 35.70% (Direct)
Ong Hang Ping: 35.7% (indirect)
Chow Kian Hung: 35.7% (indirect)
Stellar One: 5.71%
Basil Power: 11.59%

Directors & Key Management Remuneration for FYE2023 (from Revenue & other income 2022)
Total director remuneration: RM2.068mil
key management remuneration: RM0.200 mil - 0.250mil
total (max): RM2.318 mil or 11.39% 

Use of funds
1. Business expansion: 4.88%
2. Capital expenditure: 5.42%
3. Working capital: 58.72%
4. Repayment of bank borrowings: 20.46%
5. Listing Expenses: 10.52%
Conclusions (Blogger is not wrote any recommendation & suggestion. All is personal opinion and reader should take their own risk in investment decision)
Overall is a good IPO with discounted price compare to it competitors in same industry. 

*Valuation is only personal opinion & view. Perception & forecast will change if any new quarter result release. Reader take their own risk & should do own homework to follow up every quarter result to adjust forecast of fundamental value of the company.

Wednesday, September 14, 2022

COSMOS TECHNOLOGY INTERNATIONAL BERHAD

Copyright@http://lchipo.blogspot.com/
Follow us on facebook: https://www.facebook.com/LCH-Trading-Signal-103388431222067/


***Important***Blogger is not wrote any recommendation & suggestion. All is personal opinion and reader should take their own risk in investment decision.
Open to apply: 14/09/2022
Close to apply: 22/09/2022
Balloting: 27/09/2022
Listing date: 06/10/2022

Share Capital
Market cap: RM89.775 mil
Total Shares: 256.501mil shares
 
Industry CARG
Industry CARG is not enough information for analysis.
Competitor Comparison (PAT %)
Cosmos: 11.8%
Cergas Proses S/B: 3.2%
Delta Ferdana S/B: -4.2%
Mimtech Technology S/B: 4.0%
Premier water services S/B: 9.5%
SVS Engineering S/B: 9.7%
S.Kian Seng S/B: 31.0%

Business (FYE 2022)
Distribution and instrumentation services of fluid control products and manufacturing of fabricated metal products for industrial applications used in the water, wastewater and oil and/or gas industries. 

Fundamental
1.Market: Ace Market
2.Price: RM0.35
3.P/E: 15,51 @ RM0.0226
4.ROE(Pro Forma III): 12.14%
5.ROE: 21.80%(FYE2022), 26.91%(FYE2021), 8.03%(FYE2020), 45.97%(FYE2019)
6.NA after IPO: RM0.16
7.Total debt to current asset after IPO: 0.3895 (Debt:17.809mil, Non-Current Asset: 19.755mil, Current asset: 45.718mil)
8.Dividend policy: no formal dividend policy. 
9. Shariah starus: - 

Past Financial Performance (Revenue, Earning Per shares, PAT%)
2022 (FYE 30Apr): RM49.120 mil (Eps: 0.0226),PAT: 11.78%
2021 (FYE 30Apr): RM33.723 mil (Eps: 0.0218),PAT: 16.57%
2020 (FYE 30Apr): RM25.189 mil (Eps: 0.0047),PAT: 4.84%
2019 (FYE 30Apr): RM44.078 mil (Eps: 0.0206),PAT: 11.98%
 
Major customer (2022)
1. NOV (Malaysia) Sdn Bhd: 18.01%
2. National Oilwell Varco Inc: 15.63%
3. NOV Process & Flow Technologies Malaysia Sdn Bhd: 15.50%
4. Air Selangor: 9.84%
5. M8 Machinery Sdn Bhd: 7.90%
***total 66.88%

Major Sharesholders
Dato'Chong: 40.5% (direct)
MSM" 27% (direct)

Directors & Key Management Remuneration for FYE2023 (from Revenue & other income 2022)
Total director remuneration: RM1.0095mil
key management remuneration: RM0.300 mil - 0.60mil
total (max): RM1.6095 mil or 11.79% 

Use of funds
1. Acquisition of new building: 44.56%
2. Purchase of new machineries: 15.59%
3. Repayment of bank borrowing: 6.68%
4. Working capital: 19.80%
3. Listing Expenses: 13.37%
Conclusions (Blogger is not wrote any recommendation & suggestion. All is personal opinion and reader should take their own risk in investment decision)
Overall, a bit risky investment business.  The demand of the business product is very specific segment.  The company business also not easy to grow faster like other business. 

*Valuation is only personal opinion & view. Perception & forecast will change if any new quarter result release. Reader take their own risk & should do own homework to follow up every quarter result to adjust forecast of fundamental value of the company.