IPO

Tuesday, December 13, 2022

DS SIGMA HOLDINGS BERHAD

Copyright@http://lchipo.blogspot.com/
Follow us on facebook: https://www.facebook.com/LCH-Trading-Signal-103388431222067/

***Important***Blogger is not wrote any recommendation & suggestion. All is personal opinion and reader should take their own risk in investment decision.
Open to apply: 13/12/2022
Close to apply: 21/12/2022
Balloting: 27/12/2022
Listing date: 06/01/2023

Share Capital

Market cap: 264mil (will depend on final IPO price)
Total Shares: 480mil shares
 
Industry CARG (2017-2021)
Consumption value of paper cartons: CARG 10.6%
Consumption value of plastic packaging: CARG 11.3%
Competitors comparison (Net profit margin, PE)
1. DS Sigma Group: 17.7% (PE12.56)
2. Public Packages Holdings Bhd: 12% (PE4.56)
3. Jishan Bhd: 10.8% (PE6.01)
4. HPP Holdings Bhd: 9.9% (PE15.6)
5. Magni-Tech Industries Bhd: 9.3% (PE7.91)
6. Master-Pack Group Bhd: 9.4% (PE7.25%)
7. Others (9company): 8.9% to -19%

Business (FYE 2022)
Manufacturing of corrugated paper packaging products including cartons, protective packaging and paper pallets. 
DS Manufacturing: Manufacture of corrugated paper packaging products.
DS Packaging: Manufacture of corrugated paper packaging products and supply of protective packaging products.
Kaisung: Supply of protective packaging products.

Fundamental
1.Market: Ace Market
2.Price: RM0.55
3.P/E: 12.56 @ RM0.0438
4.ROE(Pro Forma III): 22.36%
5.ROE: 42.69% (FYE2022), 73.27%(FYE2021), 43.51%(FYE2020), 74.72%(FYE2019)
6.NA after IPO: RM0.20
7.Total debt to current asset after IPO: 0.3829 (Debt: 23.204mil, Non-Current Asset: 58.647mil, Current asset: 60.596mil)
8.Dividend policy: no formal dividend policy. 
9. Shariah starus: Yes

Past Financial Performance (Revenue, Earning Per shares, PAT%)
2022 (FYE 30Jun): RM121.218 mil (Eps: 0.0438),PAT: 17.71%
2021 (FYE 30Jun): RM127.858 mil (Eps: 0.0423),PAT: 16.52%
2020 (FYE 30Jun): RM85.891 mil (Eps: 0.0202),PAT: 11.55%
2019 (FYE 30Jun): RM105.682 mil (Eps: 0.0312),PAT: 14.13%

Operating cashflow vs PBT
2022: 94.09%
2021: 66.14%
2020: 70.23%
2019: 86.71%

Major customer (2022)

1. Samsung Electronics: 20%
2. SOEM (Sony): 18.86%
3. SSCSM (Sony): 17.8%
4. PAACM (Panasonic): 14.97%
5. YH Precision (M) Sdn Bhd: 5.11%
***total 75.64%

Major Sharesholders
Lucille Teoh Soo Lien: 61% (indirect)
Beh Seng Lee: 61% (indirect)
DS Kaizen: 61% (direct)

Directors & Key Management Remuneration for FYE2023 (from Revenue & other income 2022)
Total director remuneration: RM7.454mil
key management remuneration: RM0.90 mil - RM1.10 mil
total (max): RM8.554mil or 19.89% 

Use of funds
1. Expansion of operations to Penang: 2.39%
2. Establishment of Klang Factory 2: 31.91%
3. Purchase of Automated and robotic packing machines: 14.16%
4. Purchase of Honeycomb board machines: 6.38%
5. Purchase of 6-colour flexographic printing machine: 11.37%
6. Establish packaging design and innovation centre: 2.27%
7. Repayment of bank borrowings: 11.96%
8. Working capital: 10.79%
9. Listing Expenses: 8.77%
Conclusions (Blogger is not wrote any recommendation & suggestion. All is personal opinion and reader should take their own risk in investment decision)
Overall is a good IPO. Just worries part is IPO PE offer is above the average of the same industry competitors. In other meaning is good IPO with no discount offer compare to competitors. 

*Valuation is only personal opinion & view. Perception & forecast will change if any new quarter result release. Reader take their own risk & should do own homework to follow up every quarter result to adjust forecast of fundamental value of the company.

L&P GLOBAL BERHAD

Copyright@http://lchipo.blogspot.com/
Follow us on facebook: https://www.facebook.com/LCH-Trading-Signal-103388431222067/

***Important***Blogger is not wrote any recommendation & suggestion. All is personal opinion and reader should take their own risk in investment decision.
Open to apply: 13/12/2022
Close to apply: 19/12/2022
Balloting: 21/12/2022
Listing date: 03/01/2023

Share Capital
Market cap: 168mil (will depend on final IPO price)
Total Shares: 560mil shares
 
Industry CARG (2017-2021)
Wooden industrial packaging industry, Malaysia, 2017- 2021: CAGR 5.11%
Industrial packaging industry, Vietnam, 2017-2021e: 19.52%
Competitors comparision (PAT%) 
L&P group: 11.85%
ETH Holdings Sdn Bhd: 2.32%
Transpak Worldwide Sdn. Bhd: 6.06%
EPE Packaging (Penang) Sdn Bhd: 0.98%
LHT Holdings Limited (its subsidairy): 9.99% (PE6.85)
Nefab (Malaysia) Sdn Bhd: 9.41%
TimberTech Pallet Systems Sdn Bhd: -0.98%

Business (FYE 2022)
Design and manufacture of integrated wooden based industrial packaging solutions. 
Boxes, crates & packing services: 69.97%
Pallets: 27.03%
Provision of circular supply services: 0.85%
Trading as value added sevice: 2.15%
Revenue by Geo
M'sia: 81.39%
Vietnam: 18.61%

Fundamental
1.Market: Ace Market
2.Price: RM0.30
3.P/E: 11.72 @ RM0.0256
4.ROE(Pro Forma III): 18.46%
5.ROE: 36.09%(FYE2021), 35.34%(FYE2020), 23.96%(FYE2019)
6.NA after IPO: RM0.13
7.Total debt to current asset after IPO: 0.704 (Debt: 61.656mil, Non-Current Asset: 47.819mil, Current asset: 87.578mil)
8.Dividend policy: proposed 20%-50% PAT dividend policy. 
9. Shariah starus: Yes

Past Financial Performance (Revenue, Earning Per shares, PAT%)

2022 (FYE 30Jul, 7mths): RM83.824 mil (Eps: 0.0142),PAT: 9.47%
2021 (FYE 31Dec): RM120.924 mil (Eps: 0.0256),PAT: 11.85%
2020 (FYE 31Dec): RM88.305 mil (Eps: 0.0176),PAT: 11.16%
2019 (FYE 31Dec): RM66.304 mil (Eps: 0.0078),PAT: 6.63%

Profit before tax vs cash from operating
2022: 49.61%
2021: 50.46%
2020: 41.30%
2019: 14.79%

Major customer (2022)

1. First Solar Group of Companies: 55.39%
2. Jinko Solar Group of Companies: 12.12%
3. Customer A: 4.9%
4. Celestica Electronics (M) Sdn Bhd: 3.11%
5. Flextronics Group of Companies: 2.19%
***total 77.71%

Major Sharesholders

B Pack Holdngs Sdn Bhd: 64.51% (direct)
Ooi Lay Pheng: 64.51% (indirect)
Lee Soon Swee: 64.51% (indirect)
Ooi Hooi Kiang: 4.7% (indirect)
Ooi Kah Hong: 4.7% (indirect)
Moviente: 4.7% (direct)

Directors & Key Management Remuneration for FYE2023 (from Revenue & other income 2022)

Total director remuneration: RM0.843mil
key management remuneration: RM0.95mil - RM1.2mil
total (max): RM2.043 mil or 11.93% 

Use of funds
1. Capital expenditure: 29.5%
2. Business expansion: 5.9%
3. Repayment of borrowings: 14.75%
4. Working capital: 38.35%
5. Listing Expenses: 11.50%
Conclusions (Blogger is not wrote any recommendation & suggestion. All is personal opinion and reader should take their own risk in investment decision)
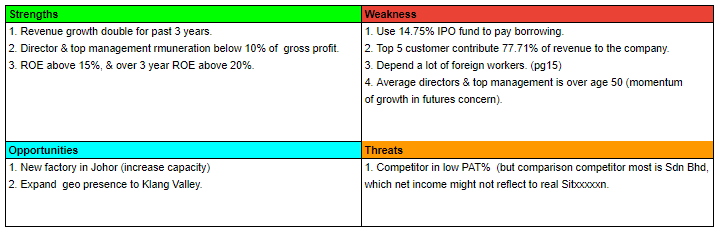
Overall is a fair IPO. The company have opportunities to growth when it finish set-up the Johor factory. 

*Valuation is only personal opinion & view. Perception & forecast will change if any new quarter result release. Reader take their own risk & should do own homework to follow up every quarter result to adjust forecast of fundamental value of the company.
NATIONGATE HOLDINGS BERHAD

Copyright@http://lchipo.blogspot.com/
Follow us on facebook: https://www.facebook.com/LCH-Trading-Signal-103388431222067/

***Important***Blogger is not wrote any recommendation & suggestion. All is personal opinion and reader should take their own risk in investment decision.
Open to apply: 12/12/2022
Close to apply: 30/12/2022
Balloting: 04/01/2023
Listing date: 12/01/2023

Share Capital
Market cap: 788.094mil (will depend on final IPO price)
Total Shares: 2.0739bil shares
 
Industry CARG
Forecast M'sia EMS industry 2022-2027 CARG: 10.3%
Competitor comparison
NGH: 7.8% (IPO PE11.9)
ATAIMS: -1.9% (PE-6.74)
Aurelius: 6% (PE30)
PIE: 5.9% (PE16)
SKPRES: 7.5% (PE14.51)
SMT technologies: 3% (GE, PE12)
VS: 6% (PE21.2)

Business (FYE 2022)
EMS provider focusing on the assembly and testing. 
(a) electronic components and products to produce completed PCBs, semi-finished subassemblies and fully-assembled electronic products.
(b) semiconductor devices.
Revenue by Geo
Msia: 74.4%
Others: 25.6%

Fundamental
1.Market: Ace Market
2.Price: RM0.38
3.P/E: 11.9 @ RM0.0318
4.ROE(Pro Forma III): 19.90%
5.ROE: 38.20%(FYE2021), 27.37%(FYE2020), 6.16%(FYE2019)
6.NA after IPO: RM0.16
7.Total debt to current asset after IPO: 0.84 (Debt: 457.459mil, Non-Current Asset: 248.833mil, Current asset: 544.138mil)
8.Dividend policy: no formal dividend policy. 
9. Shariah status: Yes

Past Financial Performance (Revenue, Earning Per shares, PAT%)
2022 (FYE 30Jun, 6mths): RM426.002 mil (Eps: 0.0159),PAT: 7.8%
2021 (FYE 31Dec): RM760.870 mil (Eps: 0.0276),PAT: 7.8%
2020 (FYE 31Dec): RM566.246 mil (Eps: 0.0148),PAT: 5.4%
2019 (FYE 31Dec): RM325.998 mil (Eps: 0.0025),PAT: 1.6%

Operating cashflow vs Profit before Tax (amended)
2022: 13.37%
2021: 46.19%
2020: 139%
2019: -ve

Major customer (2022)
1. Company A (Fully-assembled electronic products): 54.8%
2. Company B (Fully-assembled electronic products): 10.5%
3. Robert Bosch Power Tools Sdn Bhd (Completed PCBs): 9.2%
4. Company C (Completed PCBs): 5.6%
5. Company B (Completed PCBs): 2.9%
***total 83%

Major Sharesholders
Ooi Eng Leong: 57.8% (direct)
Tan Ah Geok: 7.2% (direct)

Directors & Key Management Remuneration for FYE2023 (from Revenue & other income 2022)
Total director remuneration: RM2.783mil
key management remuneration: RM1.45mil - RM1.70mil
total (max): RM4.483 mil or 7.488% 
Use of funds
1. Purchase of machineries and equipment: 3.6%
2. Working capital requirements: 29.2%
3. Repayment of bank borrowings: 63.8%
4. Listing Expenses: 3.4%

Conclusions (Blogger is not wrote any recommendation & suggestion. All is personal opinion and reader should take their own risk in investment decision)
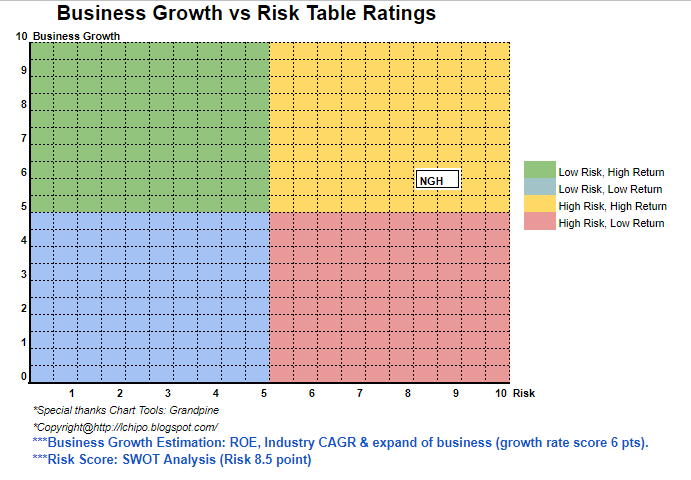
Overall is a low net profit margin industry. The operating cashflow vs PBT drop below 20%, & risk of highly depend on foreign worker. Hence, this IPO will category into high risk category area for rating. (Amended) 

*Valuation is only personal opinion & view. Perception & forecast will change if any new quarter result release. Reader take their own risk & should do own homework to follow up every quarter result to adjust forecast of fundamental value of the company.

Saturday, November 26, 2022

ITMAX SYSTEM BERHAD

Copyright@http://lchipo.blogspot.com/
Follow us on facebook: https://www.facebook.com/LCH-Trading-Signal-103388431222067/


***Important***Blogger is not wrote any recommendation & suggestion. All is personal opinion and reader should take their own risk in investment decision.
Open to apply: 25/11/2022
Close to apply: 01/11/2022
Balloting: 05/12/2022
Listing date: 13/12/2022

Share Capital
Market cap: mil (will depend on final IPO price)
Total Shares: 1.028bil shares
 
Industry CARG (2017-2021)
GVA of Digital Economy: 6%
Competitors Netprofit margin%
ITMAX Group: 36.7%
EV-Dynamic S/B: 1.7%
Signify Malaysia S/B: 1.6%
TNB Research S/B: 3.5%
ITRAMAS Corporation S/B: 2.0%
Industronics Bhd: -11.8%
Turbine Technique (M) S/B: 9.9%
Norangkasa Enterprise S/B: 1.0%
VADS Lyfe S/B: 40.4%

Business (FYE 2022)
Supply and installation and provision of public space networked systems. 
(Networked lighting systems, networked traffic management system, Networked video survelliance facilities, & other for local gov & ministry, telecommuications services providers.)
Revenue by Geo
Msia: 100% (Selangor, KL, Sabah)

Fundamental
1.Market: Main Market
2.Price: RM1.07
3.P/E: 37.7 @ RM0.0284 (PE will difference if final IPO price is not RM1.07)
4.ROE(Pro Forma III): 12.03%
5.ROE: 54.22%(FYE2021), 41.28%(FYE2020), 8.83%(FYE2019)
6.NA after IPO: RM0.25
7.Total debt to current asset after IPO: 0.456 (Debt: 115.185mil, Non-Current Asset: 119.718mil, 
Current asset: 252.331mil)
8.Dividend policy: target 20% PAT dividend policy. 
9. Shariah starus: Yes

Past Financial Performance (Revenue, Earning Per shares, PAT%)
2022 (FYE 30Jun, 6mths): RM40.740 mil (Eps: 0.01503),PAT: 37.9%
2021 (FYE 31Dec): RM79.759 mil (Eps: 0.02844),PAT: 36.7%
2020 (FYE 31Dec): RM47.538 mil (Eps: 0.01232),PAT: 26.7%
2019 (FYE 31Dec): RM37.212 mil (Eps: 0.00153),PAT: 4.2%

Major customer (2022)
1. DBKL: 94.5%
2. Norangkasa Enterprise Sdn Bhd: 2.0%
3. Bank Rakyat: 0.9%
4. Wbe Digital Sdn Bhd: 0.6%
5. Ahmad Zaki Sdn Bhd: 0.5%
***total 98.5%
***DBKL Remaining order book: 438mil (until 2029), 10.757mil(until 2023), 60.740mil(until2023)

Major Sharesholders
Tan Sri Dato’ (Dr.) Tan Boon Hock: 51.3% (indirect)
Datin Afinaliza: 17.6% (indirect)
Tan Wei Lun: 51.3% (indirect)
Directors & Key Management Remuneration for FYE2023 (from Revenue & other income 2022)
Total director remuneration: RM1.443mil
key management remuneration: RM0.80mil - RM0.95mil
total (max): RM2.393 mil or 4.48% 

Use of funds
1. Smart city application expansion to other local governments, federal ministries, and existing customers: 41.7%
2. Expansion of R&D capabilities: 6.1%
3. Expansion into enterprise market: 9.8%
4. Network and telecommunication infrastructure expansion: 19.4%
5. Working capital: 14.3%
6. Repayment of borrowings: 3.9%
7. Listing Expenses: 4.8%
Conclusions (Blogger is not wrote any recommendation & suggestion. All is personal opinion and reader should take their own risk in investment decision)
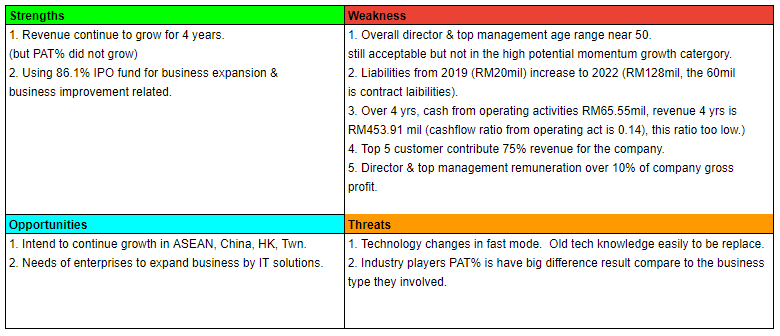
Overall is a non-discount IPO. The company have opportunities to grow but investor also must aware on the issue of over depend into single customer DBKL. (please refer to the above SWOT analysis table). 

*Valuation is only personal opinion & view. Perception & forecast will change if any new quarter result release. Reader take their own risk & should do own homework to follow up every quarter result to adjust forecast of fundamental value of the company.

Saturday, November 5, 2022

ECA INTEGRATED SOLUTION BERHAD

Copyright@http://lchipo.blogspot.com/
Follow us on facebook: https://www.facebook.com/LCH-Trading-Signal-103388431222067/

***Important***Blogger is not wrote any recommendation & suggestion. All is personal opinion and reader should take their own risk in investment decision.
Open to apply: 04/11/2022
Close to apply: 11/11/2022
Balloting: 16/11/2022
Listing date: 23/11/2022

Share Capital
Market cap: RM98.175mil
Total Shares: 577.5mil shares
 
Industry CARG (2015-2021)
Global automated manufacturing solutions industry: 7.9%
Automated manufacturing solutions industry in Malaysia: 17.5%
Competitors PAT%
ECA Integrated Group: 39.9%
Aimflex Berhad:6.2% PE18
BBS Automation Penang Sdn Bhd:78.8%
DNC Automation (M) Sdn Bhd:1.0% 
Genetec Technology Berhad:26.0% PE21
Greatech:35.2%, PE38
Pentamaster:17.1%, PE33
Vitrox: PE33

Business (FYE 2022)
Automated manufacturing solution provider.
1.Integrated production systems: 84.6%
2.Standalone automated equipment: 9.9%
3.After sales service to our customers for the provision of technical support services and spare parts: 5.5%
Revenue by Geo
1. Msia: 34.2%
2. Europe: 16.1%
3. Asia: 7.0%
4. North America: 42.7%

Fundamental
1.Market: Ace Market
2.Price: RM0.17
3.P/E: 11.97 @ RM0.0142
4.ROE(Pro Forma III): 15.4%
5.ROE: 48%(FYE2022), %(FYE2021), 62.8%(FYE2020), 47.3%(FYE2019)
6.NA after IPO: RM0.08
7.Total debt to current asset after IPO: 0.21 (Debt: 10.706mil, Non-Current Asset: 5.950mil, Current asset: 49.075mil)
8.Dividend policy: target 20% PAT dividend policy. 
9. Shariah starus: -

Past Financial Performance (Revenue, Earning Per shares, PAT%)
2022 (FYE 30Jun, 8mths): RM17.816 mil (Eps: 0.0079),PAT: 25.7%
2021 (FYE 31Oct): RM20.511 mil (Eps: 0.0142),PAT: 39.9%
2020 (FYE 31Oct): RM15.367 mil (Eps: 0.0096),PAT: 36.2%
2019 (FYE 31Oct): RM7.671 mil (Eps: 0.0024),PAT: 17.8%

Major customer (2022)
1. Customer B5: 42.4%
2. Customer H: 18.7%
3. Customer C: 10.8%
4. Customer B2: 10.0%
5. Customer A2: 7.1%
***total 89.0%

Major Sharesholders
Mr.Ooi: 24.3%
Mr.Chua: 27.8%
Mr.Kang: 13.6%

Directors & Key Management Remuneration for FYE2023 (from Revenue & other income 2022)
Total director remuneration: RM1.335mil
key management remuneration: RM0.70mil - RM0.850mil
total (max): RM2.185 mil or 19% 

Use of funds
1. Acquisition of machineries: 30.2%
2. Repayment of bank borrowings: 3.9%
3. Working capital: 54.9%
5. Listing Expenses: 11%%
Conclusions (Blogger is not wrote any recommendation & suggestion. All is personal opinion and reader should take their own risk in investment decision)
Overall is a slightly above normal IPO. Investor need to take note on the cash operating cashflow is not strong, & need to be monitor for every QR result. 

*Valuation is only personal opinion & view. Perception & forecast will change if any new quarter result release. Reader take their own risk & should do own homework to follow up every quarter result to adjust forecast of fundamental value of the company.

Tuesday, November 1, 2022

INFOMINA BERHAD

Copyright@http://lchipo.blogspot.com/
Follow us on facebook: https://www.facebook.com/LCH-Trading-Signal-103388431222067/


***Important***Blogger is not wrote any recommendation & suggestion. All is personal opinion and reader should take their own risk in investment decision.
Open to apply: 01/11/2022
Close to apply: 11/11/2022
Balloting: 16/11/2022
Listing date: 25/11/2022

Share Capital
Market cap: RM240.5 mil
Total Shares: 601.250mil shares
 
Industry CARG
Enterprise IT services industry in Malaysia: 2%
Competitors PAT%
Censof: 18.1%
Dagang Net Technologies Sdn Bhd: -38.3%
Dataprp: -30.6%
Dsonic: 7.5%
Excel Force: 32.6%
HTPadu: -6.1%
Iris: 1.6%
Msniaga: 2.3%
Myeg: 43.9%
N2N: 17.6%
Omesti: -2.9%
Scicom: 11.9%
 
Business (FYE 2022)
Design and implementation of technology application and infrastructure solutions that support the fundamental business operations.
Design and delivery of technology infrastructure solutions: 50.3%
Technology infrastructure operations, maintenance and support services: 49.7%
Revenue by Geo
Msia: 57.4%
Thailand: 16.2%
Philippines: 21.1%
Others: 5.3%

Fundamental
1.Market: Ace Market
2.Price: RM0.40
3.P/E: 14.08 @ RM0.0284 (using difference EPS, pls refer reason on financial performance part)
4.ROE(Pro Forma III): 24.13%
5.ROE: 57.60%(FYE2022), 54.69%(FYE2021), 32.27%(FYE2020), 60.62%(FYE2019)
6.NA after IPO: RM0.12
7.Total debt to current asset after IPO: 0.68 (Debt: 128.173mil, Non-Current Asset: 11.502mil, Current asset: 187.457mil)
8.Dividend policy: no formal dividend policy. 
9. Shariah starus: yes

Past Financial Performance (Revenue, Earning Per shares, PAT%)
2022 (FYE 31May): RM201.063 mil (Eps: 0.0284),PAT: 8.5%
2021 (FYE 31May): RM105.224 mil (Eps: 0.0137),PAT: 7.8%
2020 (FYE 31May): RM81.616 mil (Eps: 0.0056),PAT: 4.1%
2019 (FYE 31May): RM66.006 mil (Eps: 0.0114),PAT: 10.5%
*EPS in prospecture book pg206 not use enlarged 601.250mil shares, EPS above using manual count on enlarged 601.250mil shares after IPO. 

Order Book
2023: RM160.3
2024: RM72.1
2025: RM58.2
2026: RM42.2
2027: RM13.4

Major customer (2022)

1. Customer K: 24.5%
2. Customer J: 23.3%
3. The Siam Commercial Bank: 10%
4. Customer P: 9.7%
5. Customer H: 7.5%
***total 75%

Major Sharesholders
Infomina Holdings: 55.4% (Direct)
Yee Chee Meng: 6.3% (Direct)
Lim Leong Ping @ Raymond Lim: 5.9% (Direct)
Nasimah Binti Mohd Zain: 55.4% (Indirect)
Mohd Hoshairy Bin Alias: 55.4% (Indirect)
Tan Siang Pin: 5.2%

Directors & Key Management Remuneration for FYE2023 (from Revenue & other income 2022)
Total director remuneration: RM3.434mil
key management remuneration: RM3.35 mil - RM3.55mil
total (max): RM6.984 mil or 16.67% 

Use of funds
1. R&D: 23.4%
2. Regional expansion: 17%
3. Branding, marketing & promotional activities: 2.7%
4. Working capital: 43%
5. Listing Expenses: 13.9%

Conclusions (Blogger is not wrote any recommendation & suggestion. All is personal opinion and reader should take their own risk in investment decision)
Overall is a high grow company but also come with high risk on their over top 5 customer focus & also their financial statement healthy performance. Investor invest in this stock need to always monitor their company QR & more monitor the risk involved.  

*Valuation is only personal opinion & view. Perception & forecast will change if any new quarter result release. Reader take their own risk & should do own homework to follow up every quarter result to adjust forecast of fundamental value of the company.

Friday, October 28, 2022

LEFORM BERHAD

Copyright@http://lchipo.blogspot.com/
Follow us on facebook: https://www.facebook.com/LCH-Trading-Signal-103388431222067/

***Important***Blogger is not wrote any recommendation & suggestion. All is personal opinion and reader should take their own risk in investment decision.
Open to apply: 26/10/2022
Close to apply: 11/11/2022
Balloting: 15/11/2022
Listing date: 22/11/2022

Share Capital
Market cap: RM340 mil
Total Shares: 1.481bil shares
 
Industry CARG
Malaysia steel manufacturing sales value (2018-2021): CAGR5.4%
Competitors historical PAT% range & current PE.
ChooBee: -0.3% to 20.3%, PE2.27
Astino: 4.1% to 11%, PE4.58
ATTA: -0.27% to 17.7%, PE84.38
Engtex: -0.1% to 6.5%, PE9.27
LSteel: -5.5% to 11.4%, PE3.95
LeonFB: 0.9% to 15.3% ,PE1.56
Melewar: -10.2% to 4.7% ,PE2.25
Prestar: 1.2% to 17.7%,PE1.82
Tashin: 0.2% to 16.1%  ,PE2.44

Business (FYE 2022)
Manufacturing of and trading in steel products. 
Revenue by Geo:
M'sia: 98.4%
Others: 1.6%

Fundamental
1.Market: Ace Market
2.Price: RM0.23
3.P/E: 14.4 @ RM0.016
4.ROE(Pro Forma III): 9.73%
5.ROE: 26.74%(FYE2021), 5.68%(FYE2020), -%(FYE2019)
6.NA after IPO: RM0.17
7.Total debt to current asset after IPO: 0.696 (Debt:261.109mil, Non-Current Asset: 136.017mil, Current asset: 374.917mil)
8.Dividend policy: no formal dividend policy. 
9. Shariah status: yes

Past Financial Performance (Revenue, Earning Per shares, PAT%)
2022 (FYE 30Jun): RM213,671 mil (Eps: 0.008),PAT: 5.7%
2021 (FYE 31Dec): RM373,974 mil (Eps: 0.030),PAT: 12.1%
2020 (FYE 31Dec): RM354,714 mil (Eps: 0.004),PAT: 2.0%
2019 (FYE 31Dec): RM344,581 mil (Eps: -0.001),PAT: -0.5%
 
Major customer (2022)
1. Noblelift Malaysia Sdn Bhd: 13.3%
2. Pipeworks Sdn Bhd: 7.6%
3. Tai Hoe Hardware Sdn Bhd: 4.3%
4. Metro Supplies Marketing S/B: 3.0%
5. Machmar Industries S/B: 2.8%
***total 29.00%

Major Sharesholders
1. Law Kok Thye: 51% (indirect)
2. Tianwen Holdings: 51% (Direct)

Directors & Key Management Remuneration for FYE2022 (from Revenue & other income 2022)
Total director remuneration: RM3.215mil
key management remuneration: RM0.7 mil - 0.9mil
total (max): RM4.115 mil or 8.11% 

Use of funds
1. Construction of new headquarters, warehouse storage facility and workers’ accommodation: 42%
2. Repayment of bank borrowings: 20.1%
3. Working capital: 30.6% 
5. Listing Expenses: 7.3%
Conclusions (Blogger is not wrote any recommendation & suggestion. All is personal opinion and reader should take their own risk in investment decision)
Overall this IPO is not suitable to low risk investor, as the commodities fluctuation will cause big effect to the company net profit in future. 

*Valuation is only personal opinion & view. Perception & forecast will change if any new quarter result release. Reader take their own risk & should do own homework to follow up every quarter result to adjust forecast of fundamental value of the company.